The Credit People Review: Pricing, Services, Limitations, and Is It Worth It?
· Debt Relief Guidance
Short answer: The Credit People may be worth comparing if you have credit-report errors and would rather pay for help reviewing reports, organizing disputes, and following up. But credit repair is not a shortcut to removing accurate negative information, and you can dispute errors yourself for free. This independent review examines what the service offers, what it costs, and when paying may not make sense.
Editorial and affiliate disclosure: Debt Relief Guidance is an independent educational website. We have not purchased or personally tested The Credit People’s paid service. We may receive compensation if you enroll through our clearly identified affiliate link, without an additional charge attributable to that referral. Compensation does not determine our conclusions.
What does The Credit People do?
The Credit People describes a service that reviews credit reports from the three major bureaus, challenges potentially inaccurate items, and provides an online account to monitor activity. Features vary by plan. It cannot require credit bureaus to remove accurate, current negative information or promise that a particular credit score will improve.
How much does The Credit People cost?
On its published pricing page, The Credit People lists Standard at $99 per month, Premium at $119 per month, and a six-month Premium flat-rate option at $599. Premium lists additional features such as refreshed reports and scores, creditor interventions, and escalated disputes. Pricing and plan inclusions can change, so check the current written agreement before enrolling. A November 2026 third-party comparison also reports a $19 first-work fee; because the company’s public pricing summary does not clearly reconcile that charge, ask whether any startup or other fees apply before paying.
For perspective, six months at $99 per month totals $594, while six months at $119 totals $714, before any additional charges. The $599 flat-rate option is not automatically the least expensive choice if you need help for only a short period. Confirm cancellation and refund provisions for your specific plan.
What does the free evaluation mean?
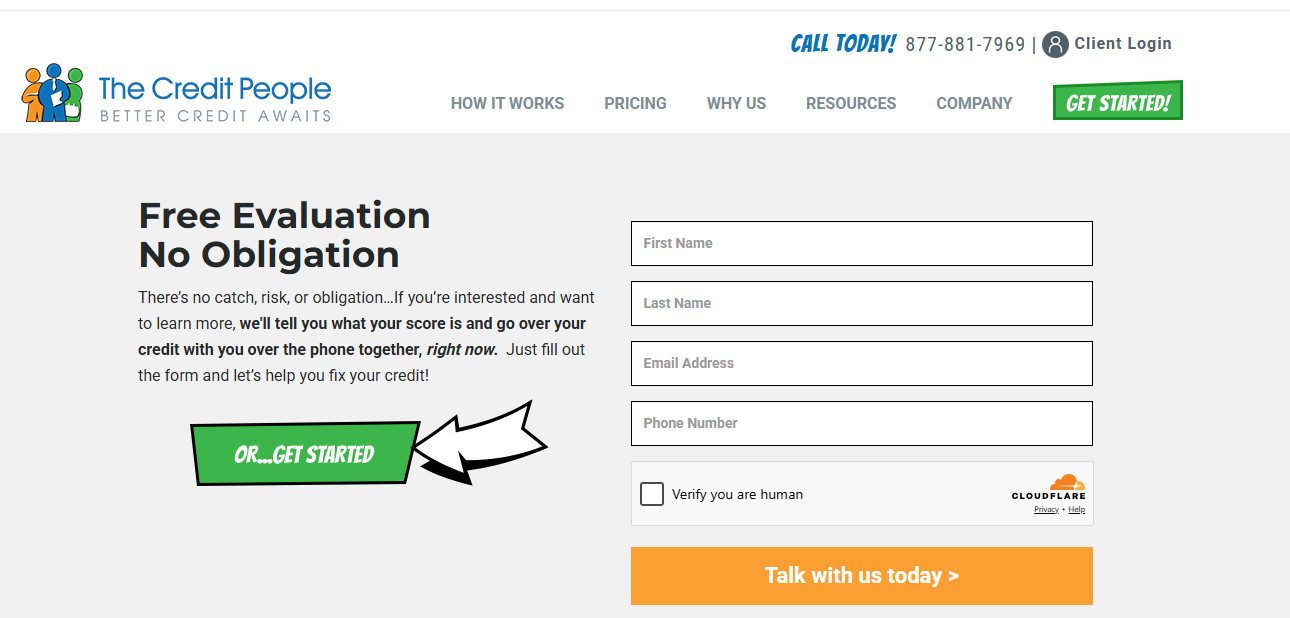
The company’s website advertises a free, no-obligation evaluation. That is an opportunity to discuss your credit situation, not a promise of free ongoing repair work. Ask what information you must provide, whether any report pull is involved, what the next step costs, and whether you are agreeing to a paid subscription.
What are the advantages and limitations?
- Potential convenience: Someone else can help organize credit-report reviews and disputes.
- Plan choice: Monthly and six-month pricing may suit different situations.
- Meaningful cost: Repeated monthly charges can add up, even if no inaccurate item is ultimately corrected.
- No special deletion power: Accurate, timely negative entries generally cannot be removed simply because a consumer hires a company.
- Results are uncertain: Testimonials and advertised score increases do not predict your outcome.
Can you do the same work yourself?
Yes. You can request free credit reports through AnnualCreditReport.com and dispute inaccurate or incomplete information directly with credit bureaus and furnishers at no cost. The Federal Trade Commission explains that legal credit-repair work can generally be done by consumers themselves for little or no cost. Keep records of the specific errors and your supporting documents. If an entry is accurate but unfavorable, a dispute alone does not entitle you to deletion.
Who might consider paying for help?
Someone facing several potentially inaccurate entries who finds paperwork or follow-up difficult may value paid organizational help. Someone with one straightforward error, a tight budget, or only accurate negative information may be better served by free disputes, budgeting, and time. Credit repair is also different from negotiating debt payments or obtaining nonprofit credit counseling.
What should you ask before enrolling?
- Which specific inaccuracies do you think can be disputed, and why?
- What will you do that I cannot do myself for free?
- What is the complete cost, including any first-work or setup charge?
- How do cancellation and the satisfaction guarantee work in writing?
- How will my personal information and credit reports be handled?
- What happens if no entries change?
Our assessment
The Credit People is a service worth evaluating for people who prefer assistance with the administrative work of credit-report disputes and understand the recurring cost. It is not necessary for everyone, and paying does not ensure a higher score, deletion of accurate information, or approval for future credit. We would start with free credit reports and identify actual errors before considering a subscription.
Optional next step: If you still want to compare professional help after reviewing the free alternatives, you can visit the company’s site to examine its current plans and evaluation process.
Affiliate disclosure: We may earn a commission if you later enroll through this link. Your decision should depend on your needs, the written terms, and free alternatives.
Explore The Credit People’s Official Website
Affiliate link. The initial evaluation is distinct from paid credit-repair services.
Related DRG guidance
For a specific reporting question, see what to check when a settled debt still appears on your credit report and whether credit repair can help after settlement.
Sources
- The Credit People: Plans and pricing
- The Credit People: FAQ and satisfaction terms
- The Credit People: Free evaluation
- FTC: Fixing Your Credit FAQs
- CNBC Select: November 2026 comparison
Reviewed November 5, 2026. General U.S. educational information, not individualized legal or financial advice. Prices, services, eligibility, and consumer circumstances may change.